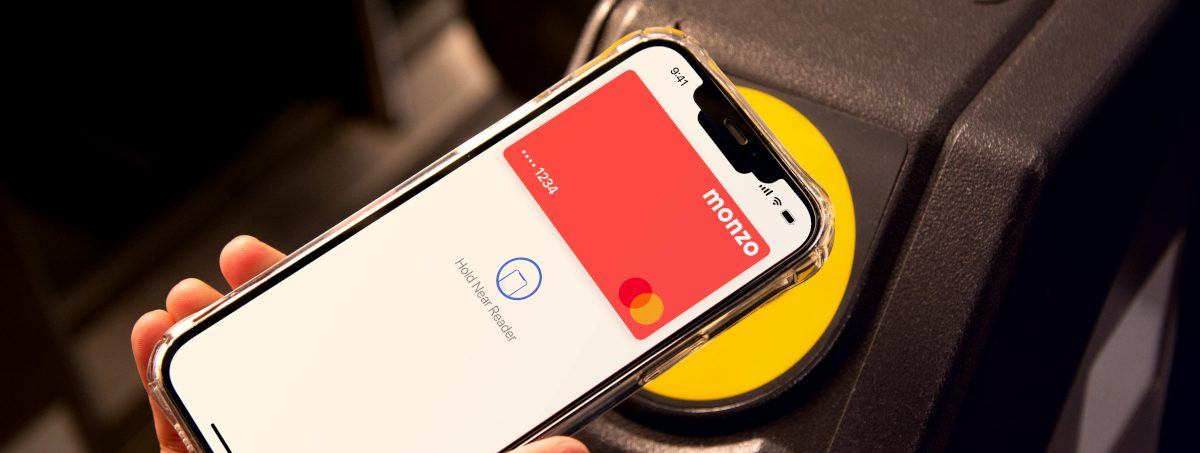
UK digital bank Monzo is reportedly weighing three paths, an acquisition by Brazil's Nubank valuing it at up to 10 billion pounds, a fresh fundraise exceeding 8 billion pounds, or a private equity stake sale, a situation that matters broadly because it could see a major digital bank change hands or ownership structure, and matters specifically to accountancy professionals because Monzo's full Irish and European banking licence means any change of control must clear a formal Central Bank of Ireland and European Central Bank review process, not just a UK regulatory sign-off.
Monzo is a UK digital bank with more than 15 million customers, which secured a full European banking licence through the Central Bank of Ireland in December 2025 and launched in Ireland in April 2026, where it is doubling its Dublin headcount to 70 staff by mid-2027.
Nu Holdings, trading as Nubank, is a Brazilian digital bank with a market capitalisation of around 65.5 billion dollars, one of the largest listed digital banking groups globally.
Monzo has engaged investment bankers from Morgan Stanley and Qatalyst to advise on its options.
The Irish dimension matters because Monzo is not simply a UK company with a UK licence. Any acquirer seeking a qualifying holding of 20 per cent or more in an Irish-authorised credit institution must file an Acquiring Transaction Notification Form with the Central Bank of Ireland, which proposes a draft decision to the European Central Bank, the body holding final authority.
That assessment can run up to 90 working days for a non-EU acquirer such as Nubank, and requires detailed business plans, ownership structures and financial disclosures well beyond a straightforward UK regulatory filing.
The private equity stake sale option under discussion, reportedly up to 15 per cent, sits just below the 20 per cent threshold that typically triggers full change-of-control review, a structural detail that could affect how quickly that route closes compared with an outright Nubank acquisition.
For the sector, a transaction of this scale involving a dual UK and Irish-regulated bank illustrates how cross-border banking deals increasingly require advisers fluent in more than one regulator's requirements, not a single domestic sign-off.
Source: Silicon Republic / Sky News / Lexology
.png)